
South Korea produced the defining transaction of the week, and the number that matters is not the size of the cheque but the multiple attached to it. Elsewhere, a shooter that moved two million copies in five days rewrote a UK publisher’s guidance, a family console maker pulled in more than $150M, and Tokyo absorbed another games-adjacent listing.
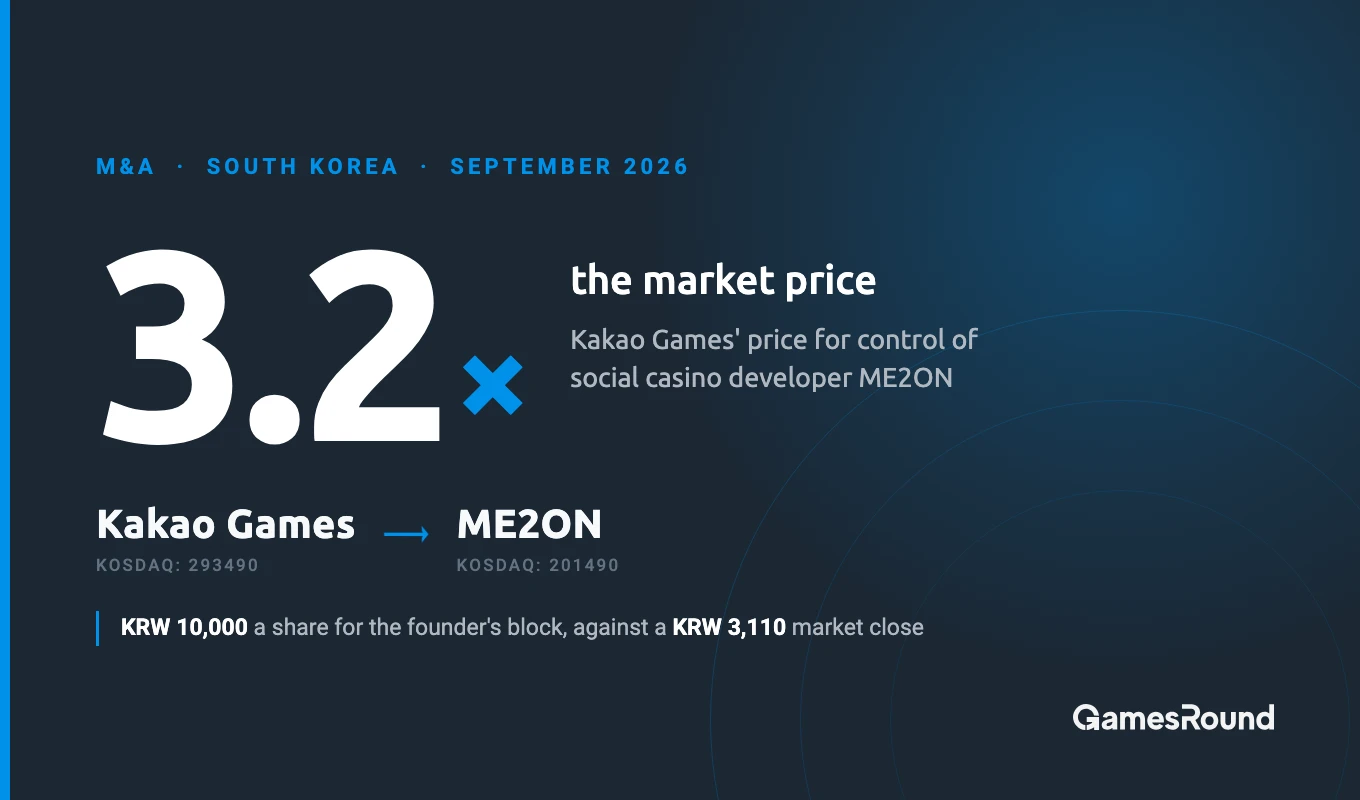
Kakao Games Takes 39.56% Of ME2ON At 3.2x The Market Price Kakao Games (KOSDAQ: 293490) is paying $72.1M (KRW 98.0B) for 39.56% of social casino and casual developer ME2ON (KOSDAQ: 201490), across two transactions its board signed off on September 15. The first is a secondary purchase: 7,011,390 shares, a 21.43% block held by founder and CEO Son Chang-wook together with eight related parties, at KRW 10,000 apiece for $51.6M (KRW 70.1B). The second is primary — ME2ON issues 9,817,118 new shares to Kakao Games at KRW 2,842, raising $20.5M (KRW 27.9B), of which KRW 19.2B goes to working capital and KRW 8.7B retires debt. Between them, the two legs hand Kakao Games 16,828,508 shares, the largest shareholding, and its own appointees on the board from closing. Settlement for both falls on November 16, 2026, pending clearance from the Korea Fair Trade Commission, with the new shares listing December 1.
The Premium Is The Story ME2ON closed at KRW 3,110 on September 14. The KRW 10,000 paid to the selling shareholders is 3.2 times that — a 221.5% control premium, and one of the widest paid for a listed Korean games asset in recent memory. Marked at the block price, ME2ON’s equity is worth $240.7M (KRW 327.2B) on a 100% basis, or 2.7x FY2025 revenue of $85.1M (KRW 120.9B) and 26.0x EBIT of $8.9M (KRW 12.6B). The market’s own view the day before was $74.9M (KRW 101.8B) — 0.8x revenue and 8.1x EBIT. Note the asymmetry inside the deal itself: the founder’s block cleared at a 3.2x premium while the new shares went out at KRW 2,842, some 8.6% below the same close. Kakao Games paid up for control and bought the fresh capital at a discount. For context on the sector, Netmarble (KOSPI: 251270) paid $2.19B for SpinX Games in 2021 at roughly 5.0x revenue, and Aristocrat (ASX: ALL) paid $990M for Big Fish Games in 2017 at 2.2x revenue and 11.9x adj. EBITDA. On revenue, then, this is not an outlier. On earnings it plainly is — which tells you the buyer is underwriting a recovery, not the last twelve months.
| TERM | DETAIL |
| Control block | KRW 10,000 per share for 7,011,390 shares (21.43%) from founder Son Chang-wook and eight related parties — 3.2x the KRW 3,110 close of September 14 |
| New shares | KRW 2,842 per share for 9,817,118 newly issued shares, 8.6% below that close. KRW 19.2B to working capital, KRW 8.7B to debt repayment |
| Total consideration | $72.1M (KRW 98.0B) — $51.6M (KRW 70.1B) to the sellers, $20.5M (KRW 27.9B) into the company, for 16,828,508 shares (39.56%) |
| Implied equity value | $240.7M (KRW 327.2B) at the block price on a 100% basis: 2.7x FY2025 revenue, 26.0x FY2025 EBIT |
| Timetable | Both legs settle November 16, 2026, subject to KFTC clearance; new shares list December 1. Kakao Games appointees replace the board at closing |
What Kakao Games Is Actually Buying ME2ON listed on KOSDAQ in 2016, six years after it was founded, and its core is social casino: Full House Casino, with more than eight million downloads across the App Store and Google Play, alongside Fulpot Poker and Classic Vegas Casino. A 45.1%-owned subsidiary, Ghost Studio (KOSDAQ: 950190), covers the casual side with the card game TriPeaks Journey and match-3 title Match Miracle: Triple Match 3D. Games accounted for 61% of FY2025 revenue at $51.5M (KRW 73.3B); a further 31%, or $26.4M (KRW 37.5B), came from talent management and drama production through Ghost Studio Entertainment, and 8%, $7.1M (KRW 10.0B), from webtoons and web novels via Bluepic and Metoon&Novel. North America supplied 65% of games revenue in Q2’26 — the asset is Korean-listed but its players are largely American.
The financial history explains both the discount ME2ON traded at and the confidence behind the premium. EBIT fell in every year from FY2021 through FY2024, from $30.1M (KRW 34.5B) at a 31% margin down to $8.7M (KRW 11.8B). FY2025 broke the run: revenue climbed 28% in won terms after a 13% decline the year before, and EBIT edged up 7% in won to $8.9M (KRW 12.6B), though margin kept slipping to 10% as the non-games businesses grew. The first half of FY2026 is the more persuasive data point — $35.2M (KRW 47.9B) of revenue at $6.4M (KRW 8.7B) of EBIT, an 18% margin, nearly double the full-year FY2025 figure.
| YEAR | REVENUE | EBIT | MARGIN |
| FY2021 | $96M (KRW 106.7B) | $30M (KRW 34.5B) | 31% |
| FY2022 | $87M (KRW 112.0B) | $21M (KRW 27.0B) | 24% |
| FY2023 | $83M (KRW 109.0B) | $17M (KRW 22.1B) | 20% |
| FY2024 | $69M (KRW 94.3B) | $9M (KRW 11.8B) | 13% |
| FY2025 | $85M (KRW 120.9B) | $9M (KRW 12.6B) | 10% |
A New Owner Spending For The First Time This is the opening move of the post-takeover Kakao Games. Japan’s LY Corporation assumed control in June through a restructuring worth around $370M and installed co-CEOs Kim Tae-hwan, previously of Nexon (TSE: 3659) and LINE Games, and Lee Si-woo. They inherited a business in retreat: FY2025 revenue fell 26% to $327.0M (KRW 465.0B) with an operating loss of $27.9M (KRW 39.6B). Kim told investors in August that more than ten domestic and international targets were under review, and was explicit that the opening bracket would be deals in the tens of billions of won rather than the hundreds. ME2ON, at KRW 98.0B, lands squarely in it. “This acquisition marks the first step in executing a merger and acquisition strategy with proven business feasibility and profitability under our new leadership, and Kakao Games will continue to pursue M&A for its future,” Lee said. It arrives a week after Align Studio, which Kakao Games backs, bought the ArcheAge MMORPG IP from XL Games for $29.2M (KRW 39.2B). Two deals in two weeks is a pattern worth watching.
In Other News
Everplay Doubles Down On Bulkhead After Wardogs Everplay Group (AIM: EVPL) has lifted its holding in Super Media Group, parent of UK developer Bulkhead, from 20% to 28% for $2.7M (GBP 2.0M), exercising an option struck in December 2025 when it took the original 20% as Bulkhead’s founders carved the studio out of Tencent-owned Splash Damage. The timing is not accidental. Bulkhead’s Unreal Engine 5 multiplayer shooter Wardogs, published by Team17, sold more than a million copies on its first day in Early Access on September 10 and two million inside five days, peaked above 400,000 concurrent players over its opening weekend, and overtook the group sales record Hell Let Loose: Vietnam had set only weeks earlier. Disclosed alongside H1 FY26 results, the step-up came with guidance that FY26 revenue and adj. EBITDA will land materially ahead of the $236.1M (GBP 175.2M) and $68.3M (GBP 50.7M) consensus. The shares are up 46.5% from the day before launch, 289p to 423.5p at the September 18 close.
Bohemia Interactive Backs Its Own Incubator Graduate Czech developer and publisher Bohemia Interactive has taken a minority stake in Warsaw-based Enjoy Studio for an undisclosed sum — its first investment in a Polish studio. The two already work together: Bohemia publishes Enjoy’s co-op first-person survival RPG Everwind, which has sold more than 300,000 copies at $24.99 since entering Early Access on March 17, 2026, and the remastered platformer Space Tail: Definitive Edition, out in August 2026. Founded in 2020, Enjoy joined the Bohemia Incubator publishing programme in 2024. The money funds Everwind‘s full release and console ports, and Enjoy retains creative independence.
Nex Raises More Than $150M For Its Living-Room Console Nex, the US maker of the family active-play console Nex Playground, has raised over $150M in equity and debt — a Series E co-led by Baillie Gifford and BAI Capital with NBA Investments, Logitech (NASDAQ: LOGI), Medici Capital Partners and The Raine Group, plus a new J.P. Morgan credit facility that accounts for roughly half the total. The motion-tracking console launched in December 2023 and has sold at $299 since April 2026 after two price rises driven by memory chip costs; it has moved more than a million units through 7,000 US stores, and the Play Pass subscriber base has grown sevenfold in 18 months to near a million. CEO David Lee, who founded the company in 2017 after building basketball-training app HomeCourt, says Nex turned profitable in 2025 — having raised just $40M in total by its $25M Series B in September 2021. The capital funds inventory and launches in Germany this year, then Japan and South Korea in 2027. Former Niantic CFO Jeff Shouger joins as CFO, and former EA chief creative officer Bing Gordon takes a board seat.
Two Smaller Rounds Worth Noting
- Tel Aviv-based Keewano raised a $12.0M Seed led by Hetz Ventures, with a16z Speedrun, Remagine Ventures, DIG Ventures and angels, timed to the general availability of KeewanoDB — an event-sequence database built for AI agents to interrogate player behaviour, churn and retention, holding every user’s full event history in order and querying 250 million events at a time. The 20-person team was founded in 2024 by CEO Mark Kardashov, COO Dima Karger and CTO Pavel Bibergal, both formerly of Plarium, and Vitaly Bukhovsky. The round funds a US expansion.
- Hyderabad-based publisher 1312 Interactive raised a $1.0M Seed led by ChimeraVC and T-Accelerate Capital, with Ventana Ventures and angels, following an undisclosed angel pre-Seed in February 2025. Founded in 2024 by Deepak Gurijala of Street Lamp Games and Raviteja Mantena, it aims at six to eight indie and AA titles a year, having shipped Winds of Arcana: Ruination in November 2025 and Palm Sugar: A Village Story in August 2026, with Souls of Bombarika and co-op party game We Are So Cooked now due in January 2027. The money covers marketing, QA, localisation and production support, plus 1312 Playground, a community platform for early player testing.
Skyfall Lists In Tokyo At A $75M Valuation Japanese reward-marketing platform operator Skyfall (TSE: 625A) has joined the Tokyo Stock Exchange Growth Market, raising $21.7M (JPY 3.46B) at JPY 1,500 a share with SBI Securities, a subsidiary of SBI Holdings (TSE: 8473), as lead underwriter. The offer combined 1.1 million new shares with 1.2 million sold by existing holders, led by CEO Hasegawa Tomokazu, and valued the company at $75.3M (JPY 12.0B). Shares opened 17.3% above the offer price before settling at JPY 1,523 on day one, up 1.5%. Skyfall’s SKYFLAG platform sells reward advertising to mobile games and apps that pays out only once a user completes an in-app action; the company also operates free-to-play Texas hold’em title Poker Chase. Revenue grew 26% to $101.7M (JPY 16.2B) in the year to September 2025, with net income of $2.8M (JPY 447M). Net primary proceeds of $9.6M (JPY 1.5B) fund US and European hiring and marketing from FY27, following a Korean entry in August 2025.
Earnings: Everplay And Huuuge
| DATE | COMPANY | PERIOD | 1-DAY REACTION |
| Tue, Sep 15 | Everplay Group (AIM: EVPL) | H1’26 | (3.6%) |
| Wed, Sep 16 | Huuuge Games (WSE: HUG) | Q2’26 | 6.0% |
Everplay’s H1 FY26 revenue fell 8% to $90.1M (GBP 66.9M) and adj. EBITDA dropped to $12.4M (GBP 9.2M) from $25.9M (GBP 19.2M), as Team17 revenue slid 16% against a release slate loaded into the second half while StoryToys grew 43% to $21.4M (GBP 15.9M). Cash stood at $76.9M (GBP 57.1M) and the interim dividend was held at 1.1p a share. Huuuge Games posted Q2’26 revenue of $50.9M, down 13.4% year on year, with adj. EBITDA of $19.8M at a 39% margin and $137.0M of cash at June 30. Direct-to-consumer reached a record 42.5% of revenue, and guidance is unchanged: a slight FY26 revenue decline with the adj. EBITDA margin at least flat on 2025.
The Week On The Market A mixed one across the tracked universe — of 61 eligible companies, 32 rose and 29 fell, with a median move of 0.2% between the September 11 and September 18 closes.
- Everplay Group (+19.97%) climbed through its results week on the Wardogs guidance upgrade. On September 18 RBC Capital Markets reiterated outperform and lifted its price target to 545p from 455p, raising its full-year revenue forecast 15% to $283.0M (GBP 211.3M) while pushing the game’s 1.0 release out to 2028.
- Huuuge Games (+9.26%) rose on the buyback rather than the numbers: $120M announced alongside Q2, equal to 164% of 2025 free cash flow, for up to 16.4 million shares at $7.30 — 36.7% of the share capital.
- Remedy Entertainment (-7.53%) fell on September 18 as the review embargo lifted on Control Resonant six days ahead of its September 24 launch. The game scored 84 on both Metacritic and OpenCritic, with 8/10 at IGN and 9/10 at GameSpot; the shares still closed down 13.5% on the day, among the largest declines on the Helsinki exchange in that session.
- 11 bit studios (-5.96%) slipped after BM Bank Millennium cut its price target to PLN 145.50 from PLN 167.00 on September 16, holding its accumulate rating while citing lower forecasts and an earlier cost underestimate, and noting $22.2M (PLN 84.6M) of net cash at the end of Q2’26.
The Week Ahead
| DATE | COMPANY | PERIOD |
| Thu, Sep 24 | Digital Bros (BIT: DIB) | FY26 |
| Thu, Sep 24 | tinyBuild (AIM: TBLD) | H1’26 |
| Fri, Sep 25 | PlayWay (WSE: PLW) | H1’26 |
The Takeaway Kakao Games’ 221.5% premium is the week’s real signal. A buyer under new ownership, carrying an operating loss and a mandate to grow by acquisition, has decided that control of a profitable social casino business with a North American player base is worth more than three times what the public market would pay for it. That is a statement about how thinly Korean small-cap games assets are valued, and about how much a strategic buyer will pay to fix that gap. Expect Kakao Games back in the market before the year is out.
Figures compiled from company filings and disclosures, with reference to InvestGame.
Don’t forget to share this post


